
How to Use a USDA Loan Calculator
Follow a USDA loan calculator guide covering loan details, ownership costs, extra payments, results, a worked example, and loan comparisons.
How does this guide help you use the USDA Loan Calculator?
This guide explains which values to enter, how the USDA Loan Calculator processes them, and how to read the resulting estimate. Follow the sections below to check assumptions, compare realistic scenarios, avoid common input mistakes, and understand when an official source or qualified professional should take priority over a planning result.
A USDA mortgage estimate combines the base purchase loan, upfront guarantee fee, recurring annual fee, fixed principal and interest, property costs and cash needed at closing. This guide explains what to enter and how to read the output without treating it as an eligibility or lending decision.
Use the USDA Loan Calculator to build a planning scenario, then compare the result with official disclosures from approved lenders.
Before You Start
Confirm the program is a plausible option before relying on its payment. USDA property eligibility, household-income eligibility and lender qualification are separate tests.
- Check the address with USDA's official property eligibility tool.
- Review the current income limit for the area and household size.
- Gather the expected purchase price and any voluntary down payment.
- Use a realistic fixed annual note-rate scenario from an approved lender.
- Estimate annual property tax, homeowners insurance, monthly HOA dues and closing costs.
- Decide whether to compare financing the upfront guarantee fee with paying it at closing.
Loan Details
- Purchase price: enter the expected contract-price scenario. The appraisal and lender decision can limit the final loan.
- Down payment: enter cash applied directly to the purchase. Qualified borrowers may be eligible for 100% financing, but a voluntary down payment reduces the base loan and guarantee fees.
- Interest rate: enter an annual fixed note rate, such as 6.25 for 6.25%. It is not a live quote.
- Upfront fee choice: select financing to add the guarantee fee to the mortgage balance, or clear the option to place it in estimated cash to close.
- Term: the calculator uses the program's 30-year fixed schedule and does not offer an arbitrary term.
Ownership Costs
Enter annual property tax, annual homeowners insurance and monthly HOA or condominium dues. The calculator adds one-twelfth of the annual amounts to principal, interest and the first-year monthly annual-fee equivalent.
Enter estimated borrower-paid closing costs. Cash to close combines the down payment and closing costs, plus the upfront guarantee fee only when it is paid in cash.
Prepaid interest, initial escrow deposits, inspections, repairs, moving expenses, reserves, discount points, lender credits, grants, seller credits and concessions are not automatically modeled. Use the Loan Estimate and Closing Disclosure for transaction-specific values.
Extra Payments
The USDA calculator models the original scheduled payment and does not apply voluntary extra principal. Its later annual-fee estimates follow the original amortization schedule used by the engine.
Transfer the financed loan amount, rate and 30-year term to the Extra Payment Calculator to test monthly, annual or one-time principal strategies. Confirm with the servicer how additional payments are applied and how they affect actual annual-fee billing.
Read the Results
- First-year monthly payment: principal, interest, annual-fee equivalent, property tax, homeowners insurance and HOA dues.
- Base USDA loan: purchase price minus the entered down payment.
- Upfront guarantee fee: the one-time fee calculated from the base loan.
- Financed loan: base loan plus the upfront fee when financing is selected.
- Cash to close: entered down payment and closing costs, plus a cash-paid upfront fee when applicable.
- Total interest and fees: scheduled interest and USDA annual fees under the calculator's assumptions.
- Annual schedule: beginning balance, principal, interest, annual fee and ending balance by year.
Worked Example
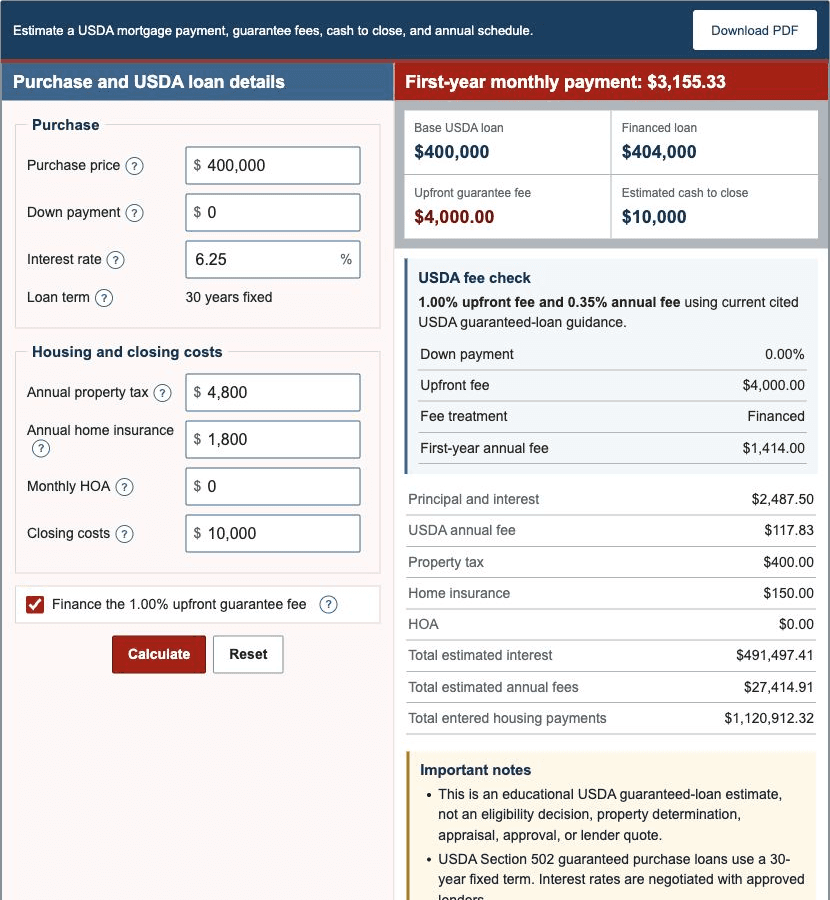
Assume a $400,000 purchase with zero down, a financed upfront fee, 6.25% fixed rate, $4,800 annual property tax, $1,800 annual homeowners insurance, no HOA and $10,000 closing costs.
- Base loan: $400,000 - $0 = $400,000.00.
- Upfront guarantee fee: $400,000 x 1.00% = $4,000.00.
- Financed balance: $400,000 + $4,000 = $404,000.00.
- Principal and interest: $2,487.50 per month.
- First-year annual fee: $404,000 x 0.35% = $1,414, or $117.83 per month.
- Property tax and insurance: $400 + $150 = $550.00 per month.
- First-year total payment: $3,155.33 per month.
- Estimated cash to close: $10,000.00.
Open Example 1 to compare this result with a cash-paid fee and a voluntary 5% down payment.
Compare Loans
Compare the complete payment, upfront cash, fees and long-term interest rather than the note rate alone.
| Option | Distinctive cost | Useful comparison |
|---|---|---|
| USDA guaranteed | Upfront and annual guarantee fees | Eligible rural property and household income |
| Conventional | PMI may apply with lower equity | Broader property availability |
| FHA | Upfront and annual mortgage insurance | Different down-payment and underwriting structure |
| VA | Funding fee for many borrowers; no monthly PMI | Service eligibility and entitlement |
Use the Mortgage Payment Calculator, FHA Loan Calculator and VA Loan Calculator with comparable price, rate and property-cost assumptions.